What Q1 2026 markdown data reveals about European fashion discounting
Price tracking data shows promotional depth varied sharply by category and market in early 2026, with some segments showing restraint while others deepened discounts.
KEY TAKEAWAYS Summary by the editors
- European fashion retailers navigated varied promotional pressures in Q1 2026 as consumer spending remained uneven across markets.
- Athleisure and casualwear categories showed different discount patterns compared to formal and occasion wear in the first quarter.
- Digital price monitoring tools have become essential for merchandisers tracking competitive positioning across channels.
- Promotional strategies diverged between value and premium segments as retailers balanced margin pressure with volume targets.
European fashion retailers faced divergent promotional pressures in the first quarter of 2026, with markdown strategies varying significantly by product category and geography. While comprehensive Q1 discount data from price intelligence platforms has not been widely published in aggregate form, merchandising executives report that promotional depth decisions reflected persistent uncertainty around consumer spending patterns, inventory positions inherited from 2025, and competitive dynamics that differed markedly between value and premium segments.
How did consumer demand shape Q1 discount levels?
The promotional environment in early 2026 was shaped by consumer caution that persisted from the previous year. European shoppers continued to prioritise value, though spending patterns varied by market and income segment. Retailers carrying excess inventory from cautious 2025 buying faced pressure to clear stock, whilst those who had managed inventory tightly maintained more pricing discipline. The contrast between discretionary categories and everyday essentials remained pronounced, with occasionwear and formal categories often requiring deeper markdowns to move stock compared to casualwear staples that benefited from sustained work-from-anywhere trends.
Which categories saw the deepest discounts?
Promotional depth varied considerably by merchandise category in Q1 2026. Based on merchandising industry discussion and retailer commentary, several patterns emerged:
- Occasionwear and formalwear faced sustained promotional pressure as demand for event dressing remained below pre-pandemic levels in many European markets.
- Outerwear saw mixed results, with winter coat markdowns influenced by weather patterns that varied across the continent.
- Athleisure and activewear maintained relatively stronger full-price sell-through in some segments, though competition intensified.
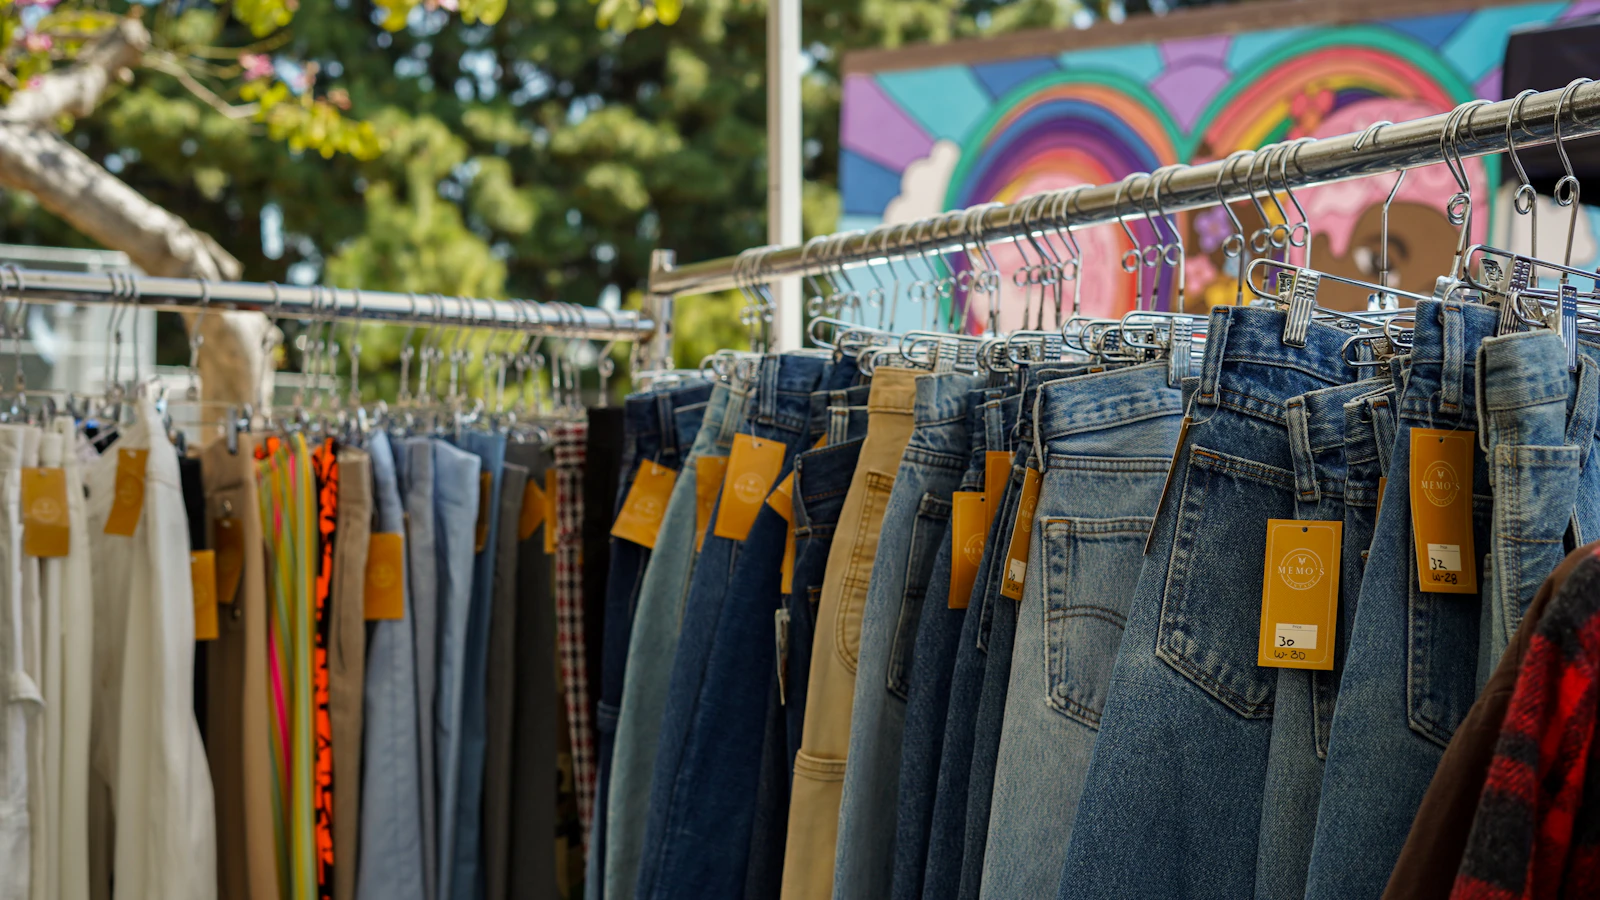
- Denim and casualwear basics showed varied promotional activity depending on retailer positioning and inventory health.
Price tracking tools enabled merchandisers to monitor competitor activity in near real-time, allowing faster tactical responses than in previous years. This technological capability meant that promotional depth could be adjusted more dynamically based on market signals, though it also risked accelerating competitive discounting in categories where multiple players were clearing similar stock.
How did discount strategies differ across European markets?
Geographic variation in promotional intensity reflected underlying economic conditions and local competitive landscapes. Markets with stronger consumer confidence generally allowed retailers to maintain more pricing discipline, whilst regions facing economic headwinds or higher unemployment saw more aggressive promotional activity. The timing of seasonal sales periods also varied, with some markets front-loading discounts in January whilst others preserved full-price selling into February. Cross-border e-commerce complicated the picture, as shoppers increasingly compared prices across markets and channels, putting pressure on retailers to harmonise promotional calendars or risk geographic arbitrage.
What role did price intelligence platforms play?
Digital price monitoring tools became increasingly central to merchandising decision-making in Q1 2026. Platforms that track competitor pricing across thousands of products and channels provided merchandisers with data to inform markdown timing, promotional depth, and product-level decisions. The technology allowed teams to identify when competitors initiated discounts, track how deeply specific items were marked down, and assess the velocity of sell-through at various price points. This intelligence supported more surgical promotional strategies, enabling retailers to target discounts to specific products or categories rather than applying blanket markdowns. However, the widespread adoption of these tools also meant that promotional moves became more visible and easier to match, potentially intensifying competitive dynamics in some categories.
How did premium versus value segments approach markdowns?
The divergence between premium and value segments was particularly notable in Q1 2026. Premium and luxury players generally maintained stricter controls on promotional depth, protecting brand equity and margin even if it meant accepting lower volume. Some premium brands limited discounts to end-of-season sale periods or used private sale channels to avoid public markdown visibility. In contrast, value and mid-market retailers often used promotional activity as a traffic driver and volume tool, accepting thinner margins to defend market share. Fast fashion players continued to rely on frequent newness rather than deep discounts on core ranges, though clearance of seasonal items remained a necessary part of the inventory cycle. The gap in promotional strategies between segments reflected different business models and customer expectations, with premium shoppers more accepting of full prices whilst value customers actively sought deals.
Looking beyond Q1, merchandising teams faced the challenge of balancing lessons from early 2026 promotional activity with the need to protect profitability for the remainder of the year. The data gathered from price intelligence platforms provided a foundation for refining promotional calendars, but success would ultimately depend on aligning inventory buys with realistic demand expectations and maintaining discipline in pricing execution across an increasingly complex omnichannel environment.
Frequently asked questions
What discount levels did European fashion retailers use in Q1 2026?
Whilst comprehensive published data on specific discount percentages is limited, industry commentary indicates that promotional depth varied significantly by category and market. Occasionwear and formalwear faced sustained pressure requiring deeper markdowns, whilst casualwear and athleisure saw relatively stronger full-price selling in some segments.
How do price intelligence platforms help merchandisers manage markdowns?
Digital price monitoring tools track competitor pricing across thousands of products and channels in near real-time, enabling merchandisers to identify when competitors discount, assess promotional depth, and make more surgical markdown decisions at the product level rather than applying blanket discounts.
Did premium and value retailers discount differently in early 2026?
Premium and luxury brands generally maintained stricter controls on promotional depth to protect brand equity and margin, often limiting discounts to end-of-season sales or private channels. Value and mid-market retailers used promotional activity more frequently as a traffic and volume driver, accepting thinner margins to defend market share.